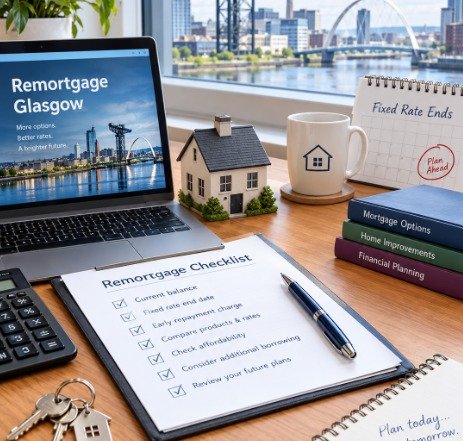
When a fixed-rate mortgage is approaching its end, homeowners have an opportunity to review the mortgage rather than simply accepting whatever happens next. A remortgage review can consider the existing lender’s options, the wider market, current affordability, property value, additional borrowing and the homeowner’s future plans.
Start the review early
Waiting until the final few weeks can create unnecessary pressure. Start by checking the mortgage balance, fixed-rate end date, early repayment charge and current product. An early review gives you time to compare a product switch with a wider remortgage. Mortgage rates can change, so early planning does not guarantee a particular future rate, but it gives you more time to understand the available routes.
Review what has changed
Your circumstances may be different from when the original mortgage was taken. Income may have changed, you may have new commitments, the property may have increased in value or you may want additional funds for improvements. These changes can affect lender affordability and product eligibility. A remortgage should therefore be based on your current financial position rather than simply repeating the original mortgage decision.
Check early repayment charges
If you leave a fixed-rate deal early, an early repayment charge may apply. Check when the charge ends and how much it would be. Sometimes arranging a future deal while remaining on the current mortgage until the end of the fixed period can be considered, depending on the lender and product. Always confirm the exact terms before committing.
Compare total cost
A mortgage with a lower rate can still have a higher overall cost if the product fee and other charges are significant. Compare the total cost over the relevant initial period and consider the term, overpayment allowance and early repayment charges. The right comparison depends on how long you expect to keep the mortgage and what you plan to do with the property.
Product switch versus remortgage
A product switch with the current lender may be straightforward, particularly when no additional borrowing is required. A remortgage to another lender may offer different criteria or products but can involve more underwriting. Neither route is automatically suitable for every homeowner. The important question is which route fits the current circumstances and objectives.
Additional borrowing
Home improvements, major expenses or debt consolidation can lead homeowners to consider additional borrowing. If you are considering this, calculate the exact amount required and understand how it changes the monthly payment, loan-to-value and total interest. Borrowing more than necessary can increase long-term costs.
Affordability still matters
A lower interest rate does not automatically mean that a mortgage is affordable. If income has fallen or commitments have increased, a new lender may assess the application differently. If additional borrowing is required, the lender will consider the new total borrowing. Prepare current income and expenditure information before assuming that a particular mortgage is available.
A Glasgow mortgage broker can help compare routes
Prestige Mortgage Solutions Ltd can review remortgage options for homeowners in Glasgow, East Kilbride and the wider UK. A broker can explain lender criteria and compare available routes, while the homeowner remains responsible for deciding which option fits their circumstances. Mortgage advice should make the trade-offs clear rather than focusing only on the headline rate.
Keep the application current
If your income, employment or borrowing changes during the remortgage process, tell the relevant professional. The lender’s assessment must be based on accurate information. Trying to proceed using outdated figures can cause delays or affect the final decision.
Review insurance and household costs too
A remortgage review is also a useful point to review the wider cost of home ownership. Buildings insurance, household bills and maintenance may have changed since the original mortgage. If additional borrowing is planned, make sure the new payment still leaves enough room for these expenses.
Think about overpayments
If your financial circumstances have improved, an overpayment facility may be valuable. Different mortgages have different limits and early repayment rules. A homeowner who expects bonuses or irregular surplus income may value flexibility. Check the product conditions before assuming that large overpayments can be made without a charge.
Consider whether you need to change the mortgage term
A remortgage can be an opportunity to review the remaining term. Extending the term can reduce the monthly payment, while shortening it can increase payments but potentially reduce total interest. The appropriate term depends on affordability and long-term plans. Do not change the term simply to produce a particular monthly figure without considering the total cost.
Check the property value before assuming you can release equity
Homeowners sometimes estimate their equity using an old property value. Before planning additional borrowing, use realistic current market information and remember that a lender may carry out its own valuation. A higher property value can improve the loan-to-value position, but it does not guarantee that a lender will use the homeowner’s preferred figure. If the valuation is lower than expected, the amount of additional borrowing available may change.
Keep a review date in your calendar
Once the new mortgage is arranged, note when the initial deal ends and when you should start the next review. Mortgage planning works better when it is treated as an ongoing financial task rather than something considered only when a fixed rate has already ended.
Understand the total cost over the deal period
When comparing products, calculate the rate, product fee and other relevant charges across the initial deal period. A slightly higher rate with a lower fee can sometimes compare differently from a lower rate with a large fee. The right calculation depends on the balance, term and expected time you will keep the product.
Check whether your credit position has changed
A remortgage with a different lender may involve a fresh credit assessment. If you have taken new loans, missed payments or significantly changed your financial commitments since the original mortgage, the available options may differ. Review your current position before assuming that a previous mortgage offer remains representative.
Review additional borrowing carefully
If you want funds for renovations, calculate the project cost using realistic quotations. Avoid borrowing a large contingency simply because equity is available. The more you add to the mortgage, the more interest can be paid over the life of the borrowing. Where possible, match the borrowing amount to the actual purpose.
Consider your future property plans
Your expected time in the property can influence the mortgage features that matter. If you may move within a few years, early repayment charges and portability may be important. If you expect to stay for a long period, the initial rate and total cost may deserve greater attention. There is no universal product structure that fits every homeowner.
Check your current mortgage statement
Before starting a remortgage comparison, obtain the latest mortgage statement and confirm the balance, interest rate, product end date and any early repayment charge. Small differences in the balance can affect the loan-to-value calculation and therefore the products available. If the statement is several months old, request an updated figure.
Review the mortgage after the rate changes
Once a new mortgage is in place, keep the product details somewhere accessible. Record the interest rate, end date, outstanding balance, early repayment terms and overpayment rules. This makes future planning easier. A homeowner should not have to search through old paperwork when the next review date approaches. If the mortgage balance falls faster than expected or the property changes significantly in value, the future loan-to-value position may also change. Treating the mortgage as an ongoing financial commitment can make later decisions more organised.
Frequently Asked Questions
When should I start planning a remortgage?
Starting several months before the current deal ends can give you time to understand the options and prepare documentation. Exact timing depends on the lender and product.
Should I stay with my current lender?
A product switch may be convenient, but it can still be useful to understand the wider market, particularly if your circumstances or borrowing needs have changed.
Can I remortgage to release money for home improvements?
Additional borrowing may be possible subject to lender affordability, property value and other criteria. Borrow only what you need and understand the total cost.
What is an early repayment charge?
It is a charge that may apply if you repay or leave a mortgage before a specified date. The amount and conditions depend on the mortgage product.
Is a lower mortgage rate always cheaper?
No. Fees, early repayment charges, term and other product conditions can affect the overall cost. Book a Free appointment now.
Conclusion
Mortgage decisions are easier to manage when the full financial picture is understood before an application is made. For readers considering remortgage Glasgow, preparation should focus on genuine affordability, lender criteria, property information and the long-term cost of the borrowing. Professional advice can help explain the available routes, but the final decision should always reflect the borrower’s own circumstances and the terms of the mortgage offered.